What Happens Behind the Scenes When an Insurer Evaluates Your Crash?
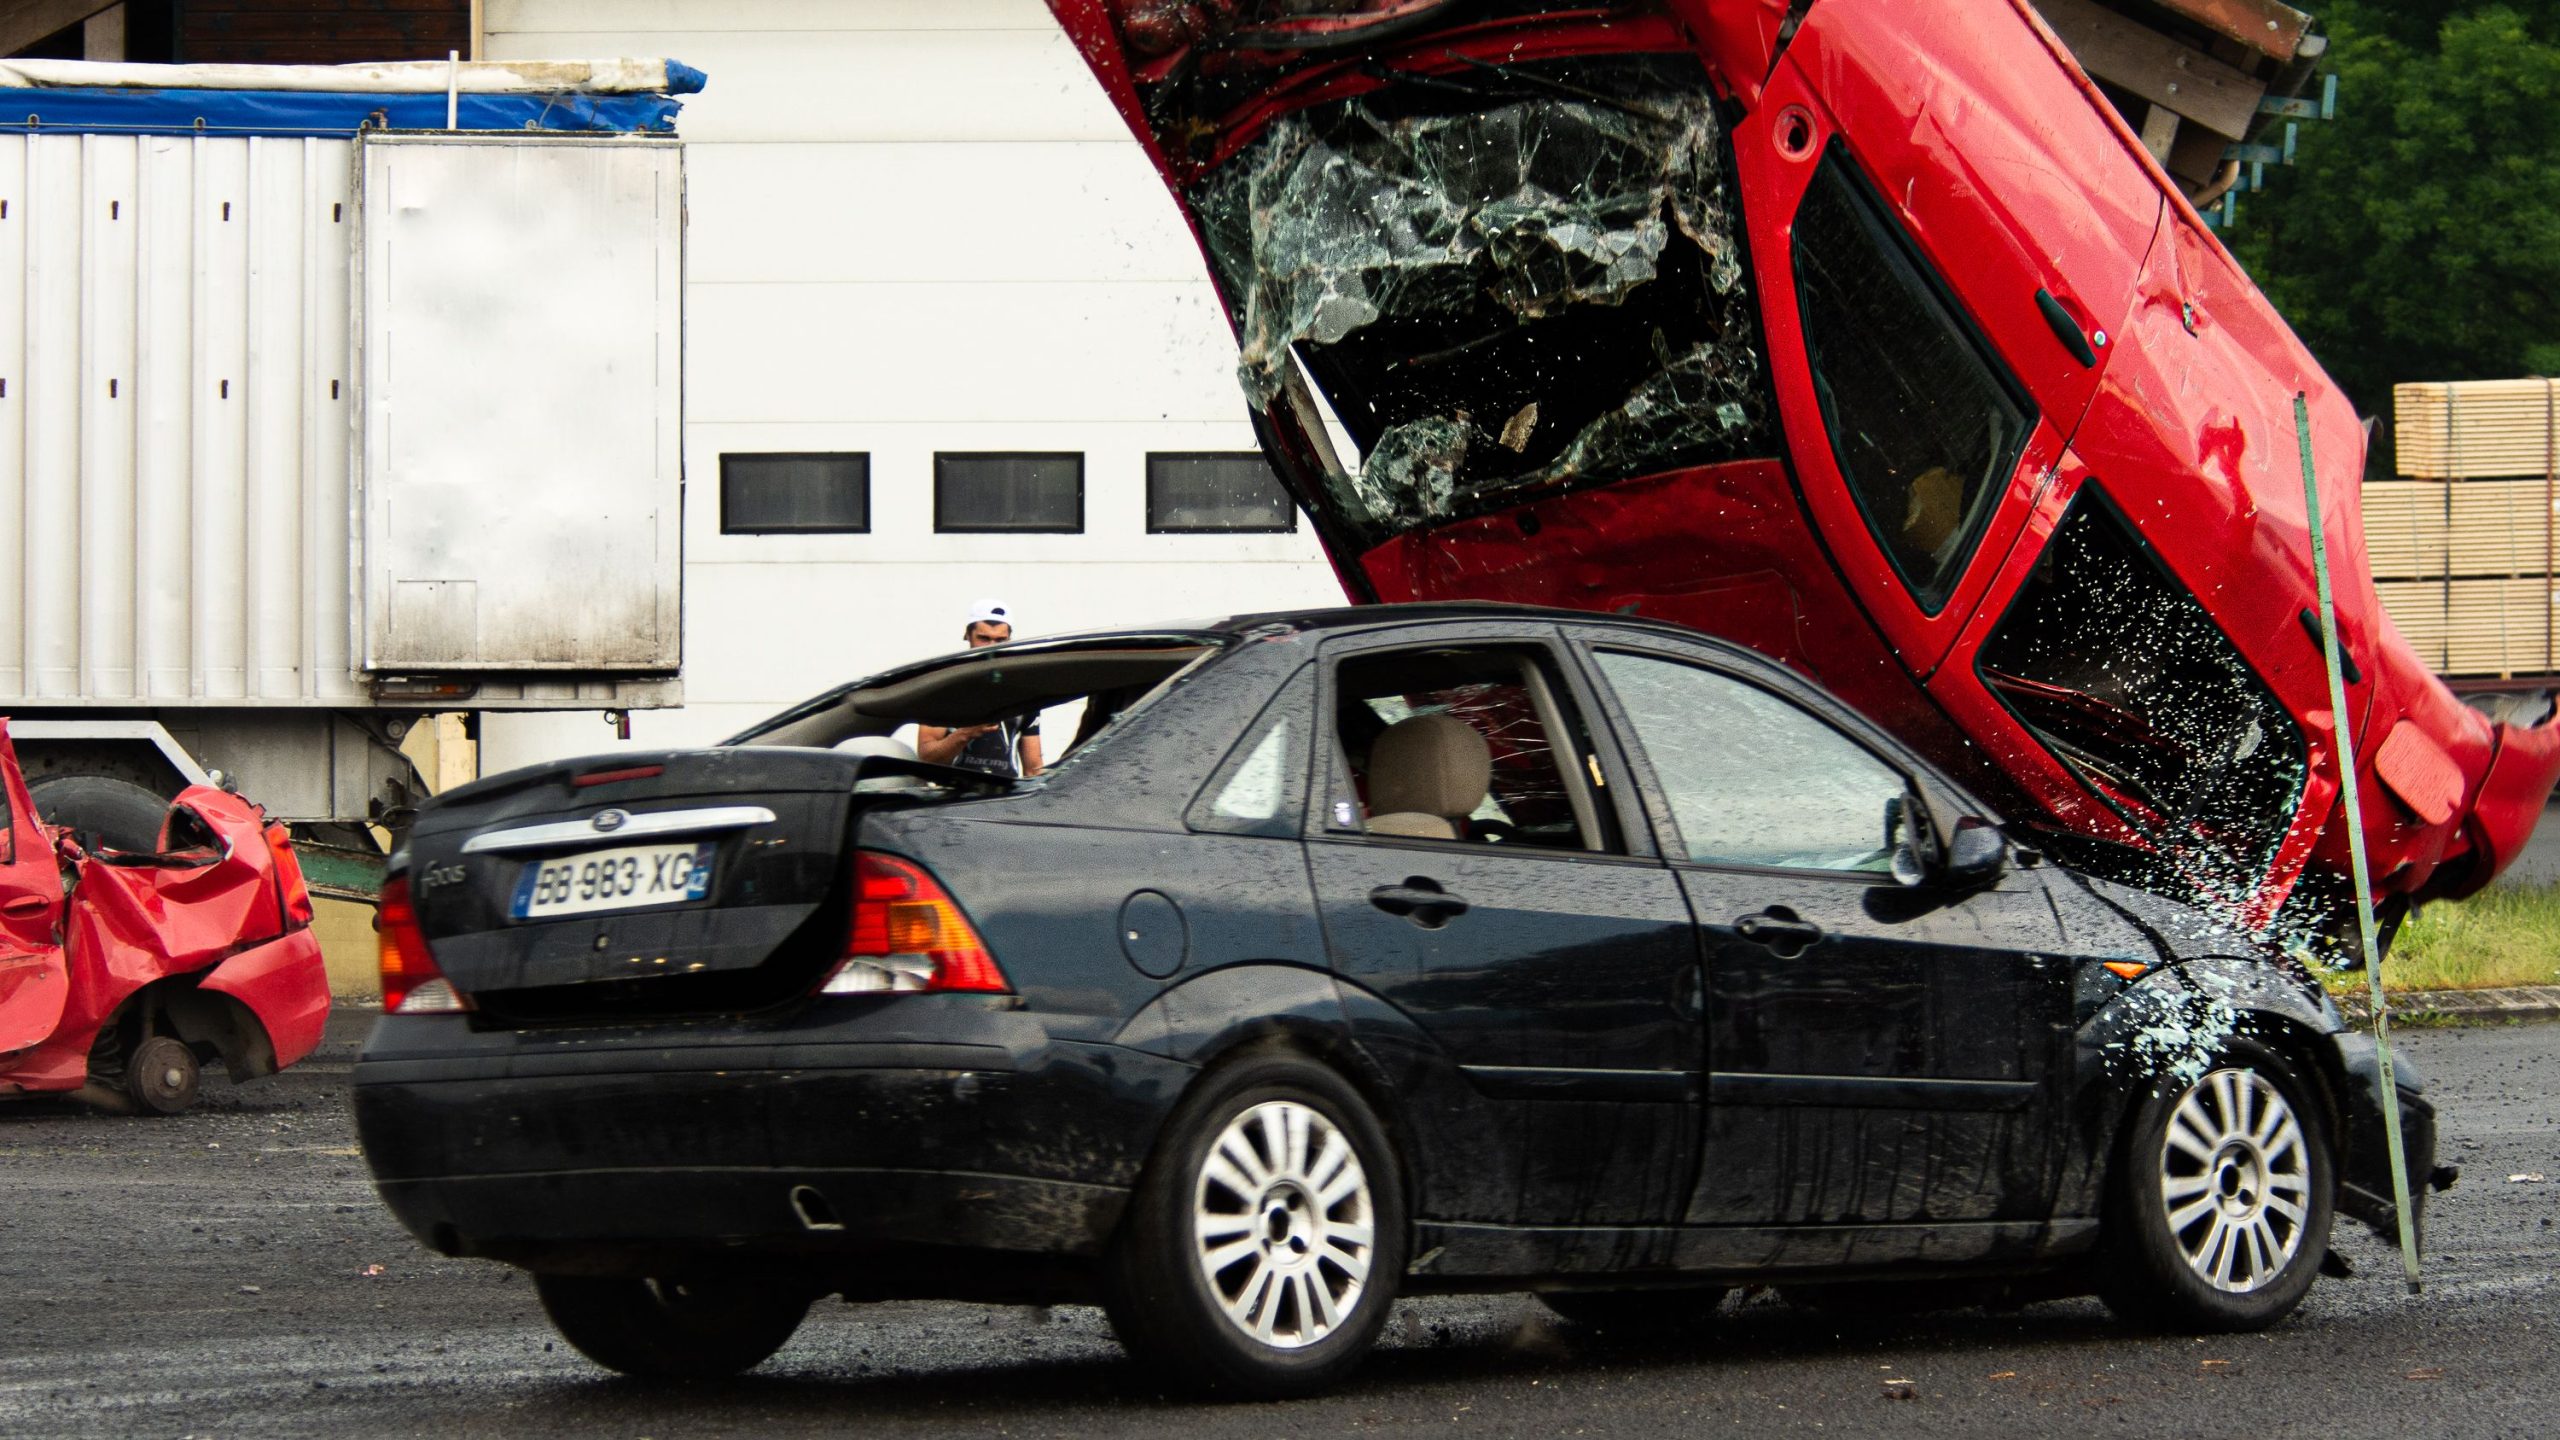
Reporting a car accident to an insurance company feels a bit like dropping a letter into a mailbox and hoping it reaches the right place. There’s a claim number, maybe a quick phone call, and then a long stretch of waiting while something happens out of sight.
That uncertainty can be stressful, especially with a damaged car in the driveway and medical appointments on the calendar. People want to know who’s looking at their claim, what they’re focusing on, and when a decision might finally arrive.
The process isn’t as mysterious as it seems. Knowing how adjusters review evidence, weigh injuries, and reach settlement figures can help anyone handling a Progressive car accident claim, or a claim with any other insurer, set realistic expectations and avoid surprises.
How Adjusters Reconstruct What Happened
Adjusters start by piecing together the crash. Police reports often provide the first outline, including vehicle positions, driver statements, citations, and the officer’s observations. Those reports aren’t the final word, but they carry a lot of weight early on.
Photographs and vehicle damage help fill in the picture. The location and depth of dents can show how vehicles collided and roughly how fast they were moving. Adjusters may inspect cars in person or rely on photos and repair estimates.
Statements from drivers, passengers, and witnesses round out the review. Adjusters often request recorded statements, compare accounts, and look for inconsistencies. Video footage, when available, can be especially powerful in confirming or challenging each person’s version of events.
Why Medical Records Can Change the Direction of a Claim
For injury claims, medical records often become the centerpiece. They show what injuries were diagnosed, what treatment was provided, and how the injured person progressed over time. Without solid records, injuries can be hard to prove. Insurers tend to scrutinize those gaps closely.
Treatment history matters a great deal. Prompt medical care after a crash helps link injuries to the accident, while long gaps in treatment can raise questions. Adjusters may also review prior medical history to see whether a condition existed before the collision.
Medical expenses and recovery expectations shape the claim’s value. Ongoing therapy, future procedures, or lasting limitations can significantly increase what a claim may be worth. That’s why claims are often harder to evaluate while treatment is still underway.
How Insurance Companies Arrive at Settlement Figures
Liability comes first. If the insurer believes its policyholder was fully at fault, it may be more willing to pay. If fault is shared or disputed, offers often reflect that uncertainty, and state fault rules can affect how much an injured person may recover.
Policy limits set an important ceiling. An insurer generally won’t pay beyond the coverage its policyholder purchased, even if damages are higher. In those cases, other coverage, like underinsured motorist protection, may become relevant. Lost wages, for instance, usually need pay stubs or employer letters to back them up.
Medical costs, lost income, and disputed damages all factor in. Adjusters weigh documented expenses, missed work, pain and suffering, and future needs against any arguments that injuries were minor or unrelated. Many insurers use internal guidelines and software to help shape those evaluations.
Why Some Claims Move Quickly While Others Stall
Missing documentation is a common culprit. If medical records, bills, wage statements, or repair estimates haven’t been provided, adjusters may hold the claim until they arrive. Organized paperwork can help keep things moving. Responding quickly to requests can shave weeks off the process.
Conflicting accounts can slow everything down. When drivers disagree about what happened and there’s little independent evidence, insurers may take extra time to investigate, interview witnesses, or request additional information. Patience often pays off, though silence for months deserves a follow-up.
Ongoing treatment and disagreements over damages create delays too. It’s hard to settle an injury claim before the full medical picture is clear, and disputes over the value of losses can drag out negotiations. Deadlines still apply, including West Virginia’s general two-year limit for filing injury lawsuits.
Conclusion
Behind every insurance claim is a detailed review of evidence, medical records, and policy terms. Adjusters reconstruct the crash, assess injuries, and weigh liability before deciding what they believe a claim is worth. Small habits like those add up over the life of a claim.
Knowing that process helps claimants stay organized and realistic. Keeping thorough records, getting prompt medical care, and responding to requests quickly can make a meaningful difference in how smoothly a claim moves forward. A rushed signature can be hard to undo.
Before accepting any offer, it’s worth making sure all losses have been considered, including future medical needs and lost income. Settlement terms are usually final, so reviewing them carefully, and asking questions when something seems unclear, can help people make decisions they won’t regret later.
 Email